Kenya’s litmus test
Two years after protests forced the withdrawal of the 2024 Finance Bill, the Treasury still needs more revenue. In a Bunge la Mayut lecture, Churchill Ogutu walks through where the 2026 bill plans to find it.
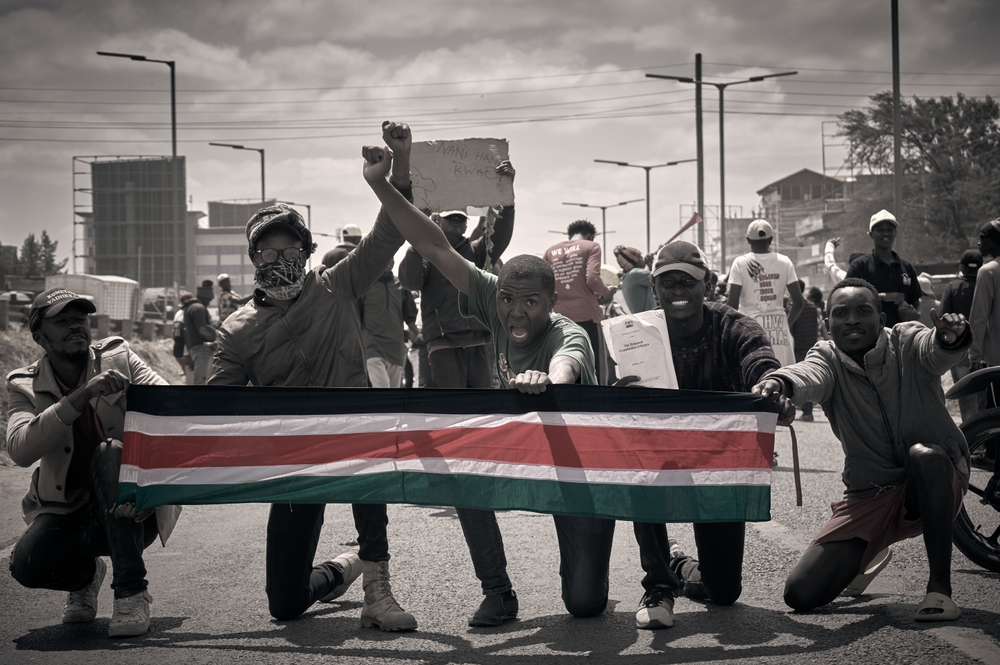
Protesters hold a Kenyan flag during the Gen Z-led demonstrations against the Finance Bill in Kenya, June 25, 2024. Photo: E-ROSH/Shutterstock.
- Interview by
- Keith Ang'ana
Kenya has a long and uneasy relationship with the Finance Bill. Every year, the Treasury returns with its plans for raising revenue, setting out the sums the country needs and the measures through which it hopes to collect them. On paper, these are questions of budgets and tax policy. In practice, they shape the terms of everyday life: what food costs, what it takes to keep a business running, how much remains in a payslip after deductions, and how far a household’s income can stretch.
The events of 2024 changed the way this conversation unfolded. Opposition to the Finance Bill grew into a nationwide protest movement, culminating in the breach of Parliament on June 25 and the eventual withdrawal of the bill. But the retreat was less an ending than a pause: some of its proposals would find their way back through the Tax Laws, Tax Procedures, Public Finance, and Business Laws Bills of 2024.
The 2025 Finance Bill emerged in the aftermath of the 2024 protests, with the government under pressure to raise revenue without reigniting public anger over taxation. The Treasury presented its proposals largely as measures to improve compliance and close loopholes, but the bill also proposed substantive changes to Value Added Tax (VAT) exemptions and other tax provisions that could increase costs for businesses and consumers. The proposed measures were expected to raise approximately KSh 25–35 billion in additional revenue.
By 2026, the pressure to raise revenue had not eased. The government was still grappling with public debt and a difficult economic climate, while households and businesses faced the question of how much more they could absorb. The proposed tax measures were projected to generate approximately KSh 98.9 billion in additional revenue, largely through administrative reforms, tax base expansion, and improved compliance. The bill sparked debate over a proposed increase in mobile phone excise duty from 10 percent to 25 percent, potential VAT changes affecting digital payment services, and proposed taxes on mitumba imports. Other concerns centered on VAT exemptions for locally manufactured goods, access to taxpayer data by the Kenya Revenue Authority (KRA), and the effect of proposed tax changes on workers’ take-home pay.
In a live lecture, Churchill Ogutu helps make sense of the Finance Bill 2026, taking its figures and proposals out of the language of legislation and placing them in their wider economic context. The government’s revised tax revenue target rises from about KSh 2.6 trillion in FY26 to KSh 2.86 trillion in FY27, with the Finance Bill expected to generate approximately KSh 98.9 billion in additional revenue from the proposed tax measures.
On May 21, 2026, four days before the deadline for public submissions on the bill, Churchill Ogutu delivered a lecture to Bunge la Mayut on the Finance Bill 2026. He set out the budget cycle and revenue targets behind the bill, then walked through its proposed amendments to seven tax laws—the Income Tax Act, the Value Added Tax Act, the Excise Duty Act, the Tax Procedures Act, the Miscellaneous Fees and Levies Act, the Stamp Duty Act, and the road maintenance levy—before fielding questions from Keith Ang’ana on the 25 percent excise duty on mobile phones, the taxation of retained profits as deemed dividends, the powers of the Kenya Revenue Authority, and the prospects for PAYE relief. A cleaned transcript follows. Shilling figures are converted to US dollars at approximately KSh 129.5 to the dollar, the prevailing rate at the time, and rounded. Submissions closed on May 25. The National Assembly passed the bill on June 18, and President William Ruto signed it into law on June 23, after MPs dropped some of its most contentious proposals, including the increase in excise duty on mobile phones.
Churchill Ogutu is head of research at Capital A Investment Bank, which he joined in April 2026 after more than 15 years in financial markets in Kenya and across Africa. He was previously an economist in IC Group’s pan-African asset management division and head of research at Genghis Capital, and is an advisor at Plato Group, a global economic and political advisory firm. He holds a BSc in actuarial science from the University of Nairobi and is a member of the Economists Society of Kenya. Keith Ang’ana is a writer based in Nairobi and the founder of Bunge la Mayut. He is a co-founder of Qwani, a youth literary publication meant to publish the works of young writers.
Read a transcript of the lecture below and watch it back here.
Good afternoon, everyone. My name is Churchill Ogutu. I’m the head of research at Capital A Investment Bank, and it’s a pleasure to be the guest lecturer for today’s Bunge la Mayut session. We’ll be discussing issues around the Finance Bill 2026. It’s a topical issue now that we’re getting toward the end of the budget cycle, and I’m happy to be here. It’s quite an interesting opportunity—and quite weird, just being alone and delivering this. I’m used to one-on-one interviews, but nonetheless, we’ll take it up.
Capital A Investment Bank is one of the leading investment banks, and as head of research I look at these issues, so I’m happy to give my two cents on the Finance Bill 2026. Today we’ll be looking at the context of the bill, and then at the different tax laws that are proposed to be amended, whether through insertions or the repeal of provisions in the existing tax laws. There are seven tax-related laws we’ll be looking at: the Income Tax Act, the Value Added Tax Act, the Excise Duty Act, the Miscellaneous Fees and Levies Act, the Tax Procedures Act, the Stamp Duty Act, and the road maintenance levy. Some of them are quite bulky, others not so much, but work with me within the context of this lecture.
To start us off, we need to look at the context of the Finance Bill. The Finance Bill conversation does not happen in a vacuum; there is a context that takes us to it. We have what you call the budget cycle, which started all the way back in August last year. The tabling of the Finance Bill 2026 in Parliament is pretty much taking us toward the tail end of that budget cycle. I think most people are used to seeing the Cabinet Secretary for the National Treasury with that briefcase on budget day, but the process starts a couple of months before we get there, and the uploading of the Finance Bill to the website some two weeks back is part and parcel of it.
So right now, after the tabling of the Finance Bill, we are undergoing public participation. We have until next week Monday, May 25, by 5 p.m., to give our submissions on the Finance Bill—and in the same breath, we also have to give our submissions on the budget estimates [Submissions closed on May 25, 2026. The bill was signed into law on June 23]. Because if you think about it, the budget is two sides of the same coin. On one side are the expenditure estimates, and on the other side is how we fund that expenditure. That’s where the Finance Bill comes in. It’s like at home: you have your budget, and you have to fund it. There are expenses you have to clear—maybe rent, maybe the shopping for the house, other things—but on the other side, you also have to finance that expenditure. That’s typically how even the national budget works: two sides. In this lecture we’ll be focusing our attention on the Finance Bill, but how does it fit into the bigger picture?
On the expenditure side, the story is what the government will spend in the next financial year. The financial year runs from July 1 to June 30 the following year. For that financial year, budget expenditure is around 4.8 trillion shillings (about $37 billion)—that’s what the government estimates it will spend. Revenue is around 3.6 trillion (about $28 billion), and the balance that has to be filled somehow comes to around 1.1 trillion (about $8.5 billion). Then there’s what we call nominal GDP.
Nominal GDP is the size of the economy over that financial year. For Kenya it’s around 20.8 trillion (about $161 billion), and it’s expected to grow by around 11.7 percent from the financial year that ends next month, in June. So the government’s assumption is that the economy grows by that amount. As the economy grows, expenses have to grow, and revenue collection grows too, because revenue is collected on the basis that the economy is growing. In addition, there are proposals the government makes to tweak the existing tax laws.
The next slide gives an overview of the tax revenue expected to be collected in the next financial year. It’s increasing by around 258 billion (about $2 billion) from the estimates for the current financial year. Among the line items, income tax is expected to grow by around 116 or 117 billion (about $900 million). There’s also some increase in excise duty, import duty, and VAT. Within this 258 billion, the government has said what it intends to collect from the new revenue-raising measures—that is, the Finance Bill, which we’ll be speaking about in the rest of the lecture—and from what we call the EAC customs measures. The countries within the East African Community (EAC), whose financial year also starts on July 1, do some revisions each year. Collectively, we’re expecting to raise 120 billion (about $930 million). So of the 258 billion, 120 billion is coming from the new revenue-raising measures, and the balance is basically from tightening administrative measures—increasing the compliance rate, using digital platforms to widen the tax base, things like that—and from the fact that, as I mentioned on the last slide, the economy is expected to grow by around 11 percent. They’re expecting that as the economy grows, they’ll be able to raise additional revenue from that. That’s pretty much the breakdown of the tax revenue.
The rest of the lecture focuses on the specific proposals contained in the Finance Bill 2026, starting with the income tax proposals. What’s the genesis of income tax? Individuals earn income in one form or another—salaries, or if you’re in consultancy, that’s a form of income that is also subject to tax. Businesses, too: the profits from businesses are typically subject to tax, and there’s a wide array of other income coming from corporates. So, my youths, in terms of income tax, this is the law that covers the income that comes in—either to a person from the work you do, or the profit a business makes, which is subject to corporate tax or another form of income tax. The government has looked at the existing Income Tax Act and is making some amendments. Remember, the last slide targeted increasing income tax by 116 billion (about $900 million), so one way of doing that is first to look at where they can raise the revenue from. So in the Finance Bill they’ve looked at the Income Tax Act and identified where the changes are to be made, and those are the income tax proposals we’ll be getting into now.
The first page looks at some of the definitions, because first and foremost, every law defines its terms so that people are clear what the tax law is all about. That’s section two of the Income Tax Act. A number of definitions have been targeted to be redefined or included afresh—issues such as immovable property.
There are two clauses in reference to that, so they are combining them so as to reduce the ambiguity that was there. There’s also the aspect of management or professional fees, which will now include interchange fees and merchant service fees arising from transactions that use a card as a means of payment. Bottom line: the people who provide card payments, or payments made via a card, will now be included under what we call management or professional fees. People have cards—you go to the bank, you do your transactions with whatever card you have—and up until now, that’s just classified as doing your transaction through a card. But under this Finance Bill proposal, going forward, the transactions around cards will be considered a management or professional fee. That is at the heart of this particular amendment.
Royalty has also been defined, but the proposal is now to widen the scope of what comes into royalty, specifically targeting businesses within the digital space. There’s a vibrancy around that sector, so the Finance Bill is targeting to widen the definition of royalty.
Then there’s winnings and withdrawals, being redefined in the context of income tax. This proposal is looking at segregating what is winnings and what is withdrawals—this is about betting. Traditionally, the last number of finance bills have been trying to widen the tax net toward the betting sector, so there’s been a raft of proposals around what counts as winnings. Say you place a bet, and then you win and eventually get 300 bob (about $2.30)—is the winnings that 300 bob, or is it what you had put in before? And then they’ve also brought in withdrawals: you’ve placed your bet, you’ve won, but what actually are you withdrawing, and through which platform? So the changes here are particularly about clarifying your income.
Then on the pension side: just clarifying that gratuity for a contract of service for a continuous period of at least three years is not a gain or profit. Some of the things being introduced in the Finance Bill are just cleanups of confusion around a particular clause, and the purpose is essentially to redefine and clarify the actual import of what the law is all about.
There’s a proposal on non-residential rental income tax. If you look at the way the law is currently, there is a withholding tax at a rate of 30 percent on immovable property—immovable property being, obviously, houses, land, and so on. So there’s a 30 percent withholding tax on those houses so long as the owner is not resident in Kenya. What the bill is proposing is that this non-residential rental income tax, which is currently a withholding tax, becomes a final tax. But we need some clarity, because there’s the rental income tax that we know as Kenyans, which is around 7.5 percent. That is rental income tax; it is not a withholding tax. Whereas for non-residents, rental income tax is a withholding tax. So there’s some confusion, because the way the law is currently, it’s subject to withholding tax, and yet they’ve now brought this proposal to impose a non-residential rental income tax. That’s something we’ll find out more about in the coming days as public participation continues.
There are some other proposals here, like the inclusion of the sale of scrap metal, and also winnings, within the context of management or professional fees, royalties, interest, and rents. That’s something for people dealing in scrap metal.
So they’re trying to bring that within the ambit of management or professional fees. I’ll rush through the next slide because it’s quite detailed. Here we’re looking at employees of the Central Bank of Kenya (CBK) getting some relief in the event they get a loan from the CBK not exceeding 360,000 (about $2,800) for the purpose of constructing, purchasing, or improving a house occupied by the employee. So in the computation of tax for a CBK employee, 360,000 of that loan will be allowed as a deduction—like a relief for CBK employees, so long as it’s for a house the employee lives in themselves, not for rental. Those are the provisions that allow you to enjoy this particular benefit.
The other aspect is country-by-country filing. They realized there was some confusion around what you call the ultimate parent entity. Multinationals operate in different countries, so there’s a requirement for country-by-country filing, and there’s also a master file framework. This proposal in the Finance Bill is bringing clarity, because there was confusion between the master file and the country-by-country report. The proposal says that a multinational with revenue of around 9.7 billion (about $75 million)—that’s the threshold—now needs to be filing country-by-country rather than a master file. So that’s some cleanup, and there are some aspects still to be known going forward.
There’s also some cleanup on insurance funds in terms of definitions: “life insurance fund” is being replaced by “statutory fund.” If you look at the Insurance Act, what it recognizes is statutory funds, but within the Income Tax Act we have what’s called a life insurance fund. So there’s a cleanup to ensure consistency in terms of what is chargeable for tax purposes, which is the statutory fund.
Now to section 24 of the Income Tax Act, and this has really generated heat over the last couple of days: this thing called avoidance of tax liability by non-distribution of dividends. You have a company. You make revenue from your sales, you pay your expenses, and then you have the profit. Ideally, if you have shareholders, you are meant to distribute part of that as dividends. But you can retain it—not distribute it, not pay out the shareholders—to expand the business. That’s what we call retained earnings. This proposal says the KRA or the Treasury have realized that some people are avoiding tax liability by not paying the dividends they are supposed to pay to shareholders. When you have retained earnings, there’s a legitimate case for paying out part of the income as dividends, but you’re not paying. So the proposal is that at least 60 percent of that part of the income is now considered a deemed dividend. If you’ve not paid out this amount that ordinarily you should be paying as dividends, at least 60 percent of that income is considered a dividend, and you have to pay tax on that dividend.
For example: you’ve made 1 million shillings (about $7,700) in income in a year, expenses are around 600,000 (about $4,600), and hypothetically 400,000 (about $3,100) is what you’ve made.
If you have not apportioned part of that income as retained earnings, it’s deemed that you have to pay that entire 400,000 as dividends—you have to distribute it to the shareholders. What this proposal says is that at least 60 percent of the 400,000 remaining, which is 240,000 (about $1,850), will be deemed to have been paid out as dividends, so 240,000 is what will be liable to tax. We’ve had lots of debate around that: it says “at least” 60 percent, so it’s discretionary—it could go from 60 percent to 80 percent to 100 percent. That’s what’s been quite contentious over the last couple of days. But anyway, we’ll be able to get more clarity going forward.
The other aspect as we move along is section 52. Section 52 of the current Income Tax Act says that filing of returns is by June 30. If your year of income is 2025, ideally you should be filing a return by June 30 for the income you got last year. But from July 1 going forward—technically for the 2026 year of income—if this proposal sails through, it means that from next year, rather than June 30, the deadline for filing returns has been brought forward to April 30. And if you are filing a nil return for this year, you have to file by January 31 next year.
Let me be the devil’s advocate here. We heard the National Treasury saying: you already know your return. Even right now, in the month of May, we know the income that employees generated, because employees already have their salary information by now. So why should you wait until June 30 to file and clog the system? If you don’t have a business, and you typically don’t earn any income, you file a nil return—so why wait until June 30? Just do it by January 31, because it’s already a nil return. That’s the National Treasury’s argument. But the counterargument is that people are saying: Wait a minute, in instances where I need to get my financials audited, that takes a while. I also need to engage my regulator—some organizations have regulators—and the board also needs to approve. So it’s a lengthier process, and filing returns in April is a bit too soon because of all the processes that have to be followed. That’s the counterargument to the proposed amendment to section 52. The other amendment is that the return of income is to be furnished to the KRA—I think that one is clear enough.
Let’s move to the First Schedule amendments. Basically, capital gains relating to the transfer of property to a real estate investment trust (REIT) will now be exempt from tax. If you have a property, or you want to own property, ownership can happen either by building the property yourself—which is quite cumbersome, probably billions of shillings—or you can come to the Nairobi Securities Exchange (NSE), where there are products like real estate investment trusts, and buy a unit of a building. Rather than buying the entire building, you’re getting ownership of that building through units. On capital gains: if you want to transfer your property, say a building you own, into a real estate investment trust, that transfer triggers what we call a capital gains issue, and as a result you are subject to capital gains tax.
But this proposal is coming in and saying: No, wait a minute, we shall exempt that tax, so that we improve the offering at the Nairobi Securities Exchange—so that if you’re a young person with some money, you can put it into a real estate investment trust, because currently such transfers complicate things. If you have a property and you can put it within the control of a real estate investment trust without the transfer attracting a tax burden, that should increase the pool of things people can invest in. I think that’s the purpose of this particular proposal.
The other proposal is around some clarity on industrial buildings in terms of investment allowance. There wasn’t a rate for it. If you’ve built an industrial building, the allowance lets you get some relief over the next, say, ten years—but there wasn’t a rate for that relief. Say you’ve built an industrial building worth 1 billion shillings (about $7.7 million). Technically, you should be able to deduct it in terms of investment allowance, meaning that when you’re calculating your taxes, you get some form of relief for a number of years as you recoup your investment. Typically, the investment allowance is there to encourage investment. But there was no rate. Now the Finance Bill says the rate will be 10 percent. So for that 1 billion, in equal installments over the next ten years, KSh 100 million (about $770,000) a year will be like a relief that helps you recover your investment over those ten years.
There are a number of other proposals here—for example, a reduction of the income tax rate for non-resident contractors in the extractive industries. In the extractives, especially with the noise we’ve been hearing about rare earth minerals in some parts of the country, we’ve seen that most of the people coming in are foreigners, not locals. Because of that, the income tax rate for non-resident contractors within the extractive sector is being reduced—right now it’s at 7.5 percent and it’s being reduced to 30 percent—to boost some of these investments. But at the same time, as they come into Kenya, into rare earths and the extractives, there’s what you call repatriated income: The profits they make, they take back to the countries they came from. So there’s an introduction of a 15 percent tax on that income they take back to the parent countries. That is a brief summary of the income tax proposals—quite a number of them, but to me, that covers income tax.
The other aspect is value-added tax (VAT). VAT is basically on the consumption of goods and services: If you purchase a good or procure a service, there’s a VAT element to that purchase. There’s a Value Added Tax Act in Kenya that deals with that. Say you go to buy stuff—a commodity, you go to the shop, you buy vegetables at the supermarket—or you go for services and you get a service. There are VAT-able items: the things you buy within the context of the standard VAT rate of 16 percent that you have to pay. When you buy those things, or services, there’s VAT on them. That’s the heart of the next set of proposals, on VAT.
The first one starts at section two. Section two of all the tax laws looks at the definitions. Here it’s basically deleting some definitions: assessment, information technology, and tax computerized system. These are things that exist within the context of VAT.
But if you go and look at the Tax Procedures Act, it also speaks to these things. So the Finance Bill is saying that if they are within the context of VAT, they should be removed, since they’re already in the Tax Procedures Act—rather than having duplication, they should sit within the Tax Procedures Act and be removed from VAT. That’s the import of the amendments we’re seeing to section two.
There are quite a number of things here, but one notable one is section 31 of the VAT Act, which speaks about refund of tax on bad debt. Say you sell to someone and you expect them to pay, including some VAT—you expect the payment, but eventually they don’t pay. The proposal is revising the timeline for the relief: It’s being pushed by another year, from two years to three years. The impact is that it will delay access to VAT refunds—rather than claiming within two years, you start claiming within three years—and potentially it could lead to cash flow issues, because maybe you were depending on that refund, but now it’s being pushed further down the road. That will lead to cash flow issues for businesses seeking refunds from the KRA.
The other issue is tax avoidance schemes. As I said, there are definitions being removed from VAT because they are already within the Tax Procedures Act (TPA), and that also applies to this particular proposal. There is a clause, section 66, which touches on tax avoidance schemes for the purposes of VAT, but there’s another proposal within the Tax Procedures Act that deals specifically with tax avoidance schemes. So that’s the cleanup—to remove it from VAT and put it within the Tax Procedures Act. That’s the proposal we’re seeing.
Another thing is around tax invoices. Right now there’s section 42, and the requirement to issue a tax invoice deals specifically with registered persons—so if you have revenue of at least KSh 5 million (about $39,000) in a given year, you are supposed to register within this ambit of a tax invoice. But now the proposal is removing “registered,” so that it remains as “persons.” It’s saying you don’t need to be a registered person; irrespective of whether you’ve registered or not, for the purposes of issuing a tax invoice, it’s for everyone. My interpretation is that this is an extended requirement, not just for people within the VAT regime but for everyone—you and me. That’s something which will be quite interesting to see if it sails through.
Then we get to the First Schedule of the VAT Act, which looks at exempt items. Exempt means that when you deliver or produce a good, you can go back and claim on some of the inputs you used. Let me give an example. Assume you’re a registered baker. You need flour, you need cooking oil, you need certain things to produce bread. So yes, you can produce bread, but at the same time, the flour and the oil you used, which you paid VAT on when you bought them—if they’re exempt, it means you can claim back the VAT you paid on the inputs you used to make the bread. That’s the upshot of what is exempt. But there’s a proposal here to move some items from exempt status to the standard rate of 16 percent.
So we have items that were under exempt status being moved to the standard rate: spacecraft; goods and services for direct and exclusive use in the construction of tourism facilities; the supply of denatured ethanol; items like direction-finding compasses, instruments, and appliances for aircraft—that’s for people with aircraft, it’s applicable to them; and spare parts imported or purchased for direct and exclusive use in the implementation of official aid projects. Initially these were exempt; now they’re being moved to the standard rate, so 16 percent will be applicable to these products.
Then there are items moving from the standard rate of 16 percent to exempt status—a number of products, but for the purposes of this lecture, the ones we’ll touch on. Scrap metal, which is at 16 percent but is being moved to exempt status—remember, under income tax we touched on the issue of scrap metal, but this is a different thing. The supply of imported or locally purchased telephones for cellular networks and other wireless networks—if you have a business importing or locally purchasing telephones, that’s currently at 16 percent VAT, but it’s being moved to an exempt category. Another item is worn clothing and other worn articles of tariff heading 6309, other than importation—there’s a buzzing industry for repurposing secondhand clothes, at the export processing zones (EPZs) for instance, and this excludes the importation. These were at 16 percent but are being moved to exempt status. Then there’s the supply of goods or services in the implementation of infrastructure projects undertaken within public-private partnerships (PPPs). There are projects being implemented under PPP—quite a number of them. I think the Rironi–Mau Summit road—yes, that’s a PPP project. And there are other projects in the pipeline. If you are delivering goods or services to any of these projects being implemented under PPP, what was 16 percent will be exempt. That’s something to spur some of the infrastructure projects, and it’s effective from July 1 if this proposal sails through.
There’s also a raft of proposals moving things from zero-rated to exempt. Zero-rated goods are those where, technically, the justification is that on one hand you have inputs, as with our bakery example, but at the same time you don’t have any justification whatsoever to push this cost to consumers. So for these goods, it’s 0 percent VAT. But now there’s a proposal to move some of these from zero-rating status to exempt status. The transportation of sugar cane from farms to milling factories was zero-rated but is being moved to exempt status. The supply of electric bicycles—at least in Nairobi you see a number of these operators; I think this is a reference to the electric motorcycles coming up, quite a number of them—will move from zero-rated to exempt status if this passes. And there’s a whole host of raw materials, locally purchased or imported, for the manufacture of artificial animal feeds, moving from zero-rated to exempt.
Okay, I think we’ve finished with value-added tax. First it was income tax, then VAT, and now we move to excise duty. There are certain products which have a specific rate of tax applicable to them. Back in the day, we used to know it as a sin tax. When excise duty came, it was a sin tax, in the sense that these taxes were brought in as prohibitive measures for tobacco, beer, and all those kinds of things. That’s how we used to know it. But is it still a sin tax? If you look at the ambit of the goods within excise duty, quite a number of them—non-alcoholic drinks and some other goods which are not necessarily bad. The difference here is that VAT touches on goods and services in a broader sense.
Either you are zero-rated, standard-rated, or exempt—or a rate which is neither standard nor zero, like petroleum at 8 percent VAT, somewhere in between. But when you look at the excise duty regime, it’s different, because it’s looking at specific goods, and then there’s a specific tax rate for each of them. Traditionally these were sin taxes, but now it’s been widened.
Section two of the Excise Duty Act seeks to add antique, vintage, or classic vehicles, so there’s a definition for that. That means that further down the line, there’s a specific tax rate applicable to these vehicles. That was the notable amendment to section two—to define what these vehicles are.
Now, this is a hot one. There’s a new section, section 6A: imposition of excise duty on locally purchased or imported telephones upon activation. Interesting. Some have made noise about it, because right now, in the context of excise duty, it’s typically upon importation—as you import goods, that’s the point where excise duty or VAT is applicable. But now we’re seeing that upon activation of a phone, locally purchased or imported, the point at which you’re activating it is where you’re paying this particular excise. That’s a new section 6A of the Excise Duty Act being introduced.
Further down, section 36 of the Excise Duty Act: payment of excise duty on cellular phones. So section 6A is saying that there will be an imposition of excise duty—from July 1, if this passes through, there’ll be duty upon activation of a phone that is either locally purchased or imported—and then section 36 speaks to the payment of excise duty on cellular phones. It’s an additional provision: Section 36 speaks about what is subject to excise duty, so it basically says there’ll be a payment of excise duty on cellular phones, bringing alive this new section 6A. Then if you go to the First Schedule, it says that 25 percent excise duty on imported cellular phones will be applicable. This particular clause takes effect from January 2027.
There are a number of other amendments too—the various rates of excise duty for antique, vintage, or classic vehicles. It’ll be 50 percent of the excisable value. So if you have an antique car—say a 1950s car—with an excisable value of KSh 1 million (about $7,700), the proposed law says you have to pay excise duty of 50 percent of that: KSh 500,000 (about $3,900) on that vintage.
So we go to the next broad proposal, the Tax Procedures Act. So far, those were the explicit taxes, but now we get to the procedures, because there are procedures for how you pay taxes, and there’s a specific law that tackles those procedures. That’s the Tax Procedures Act, and various amendments have been brought into play. Section two speaks about the deletion of “certificate of origin” and the insertion of “virtual asset service provider.” Sometime last year, we saw the Virtual Asset Service Providers Bill being passed, so it’s now an act of Parliament. Basically, it brings to the fore the fact that virtual assets are quite significant in the economy: Bitcoin, forex, digital lending within the virtual asset space, and all that. So there’s a definition of virtual asset service provider in line with that act of Parliament that was passed last year.
Then there’s a new section 6C, which still touches on virtual asset service providers—how they file information returns. They’ve assessed that Kenya is becoming more of a digital economy with all these virtual assets, so now that we have the virtual asset service providers, this is how they need to go about filing information returns. There’s also section 6D, which speaks about agreements for the automatic exchange of information with other countries on virtual asset transactions. Some transactions in the virtual asset space cut across borders, so this proposal says Kenya can now share information with other countries that have implemented this framework, to assess transactions within the virtual asset space. That’s tied to recognizing that there’s a Virtual Asset Service Providers Act in place, and trying to fine-tune how they can better target that space.
There’s the section 10 amendment on deregistration. If for one reason or another you are deregistered in terms of your PIN—you have a PIN, but you’re deregistered—then in the event that you re-register, you can still get back the same PIN, because everyone has a unique PIN number. At least it enhances continuity, because they have your records. It’s easier than having two different PINs, one up until the point you were deregistered and another new one. It ensures continuity of your tax records if you re-register after deregistration.
There’s another one, section 12 of the Tax Procedures Act. I’m within that space, in the investment bank. Right now, one of the requirements for non-residents is that they need to have a PIN as one of the know-your-customer (KYC) documentation requirements. But the Finance Bill is saying that investment banks will no longer require them to have a PIN. It’s reducing compliance costs, because it’s quite lengthy to get a PIN—I’d experienced it previously, with some foreign investors coming in to acquire a PIN; it’s a lengthy process. This one is giving a reprieve, to spur foreign investors coming into the Nairobi Securities Exchange.
Tax avoidance schemes: As we said, this was in section 66 of the VAT Act, but now there’s a new section 18A of the Tax Procedures Act that brings alive these tax avoidance schemes. So they repeal section 66 of the VAT Act and bring in a new clause under the Tax Procedures Act.
There’s another new one, quite interesting: a new section 29A, whereby the KRA—in this case the commissioner—can issue its own assessment. Right now, section 29 of the Tax Procedures Act gives a person the leeway to self-assess. But this new proposal says that over and above you as an individual conducting your self-assessment, the KRA can now come in and issue an assessment independently. There’s some concern that they’ll be overstepping their mandate, going over and above what they are required to do. That’s quite concerning, but we’ll see. We’ve had lots of noise around that.
The other aspect, which is quite an interesting one, is the tax amnesty. In the event that, for one reason or another, you’ve not paid your taxes, there’s normally some interest and some fines that you’re supposed to pay over and above the tax.
Tax amnesty basically waives all those fines and penalties—just pay the tax you’re supposed to pay. The last tax amnesty, which ran through June last year, was on the tax for the year of income ending December 2023. Now this has been extended up to last year, and you have until the end of December to pay the outstanding tax you did not pay for last year, without incurring the penalties and fees. That’s the tax amnesty. As we mentioned earlier, this tax amnesty is expected to yield KSh 30 billion (about $230 million); the last one yielded KSh 50 billion (about $390 million). It brings about an issue of moral hazard: as a taxpayer, I know that at some point the KRA or the National Treasury will come with a tax amnesty, so why should I pay the tax right now? A year or two down the line, I can benefit from a tax amnesty without incurring penalties or fines. That’s an issue coming up with this proposal to extend the tax amnesty.
There are a number of other proposals here. Section 75: The KRA may use the electronic tax system to generate pre-populated tax returns. Going forward, they’ll be able to introduce pre-populated returns in the self-assessment system, so if the KRA brings in this IT system, you’ll be able to generate pre-populated returns, and the assessment is then just going through them and confirming whether they make sense.
There’s also the repeal of the certificate of origin. One of the things we spoke about at the beginning was the definition of certificate of origin being entirely shelved, because the focus on the certificate of origin will no longer be within the Tax Procedures Act but within the East African Community Customs Management Act. That’s the whole point of repealing the definition in section two, and then section 44A repeals the certificate of origin itself. Pretty much a cleanup, to ensure that anything to do with certificates of origin is handled from a customs perspective. There are others—section 86 being replaced with a new section dealing with failure to comply with the electronic tax system, a whole host of things—but by and large, we’re pretty much done with the Tax Procedures Act.
Next we move to miscellaneous fees and levies—two or three proposals here. The first is the reduction of fees paid into the fund from 20 percent to 10 percent. There’s the import declaration fee, and a portion of it ends up in a fund, the Import Declaration Fee Fund. Initially, the portion of the fees that went into this fund was 20 percent, but the proposal is to reduce it to 10 percent. Then section nine deals with the East African Community Customs Management Act. Initially, the import declaration fee, the railway development levy, and the export levy were within the ambit of the EAC Customs Management Act, but now the proposal is to delete that reference. It means that the other levies, which did not eventually end up within the context of the East African Community, will now be included, because initially they had restricted it to just the import declaration fee, the railway development levy, and the export levy. With the deletion, whatever levies are collected will now eventually end up within the context of customs.
Coming to the tail end is the stamp duty. As we mentioned earlier with real estate investment trusts: You have a property you want to transfer, and under the income tax proposals the capital gains tax on that was exempted.
So section 96A now specifically includes instruments that transfer interest in property to a real estate investment trust. If you have a property and you want to transfer it to a REIT, that instrument will now be included within the context of stamp duty—I think just to spur the transfers we’re seeing. If you have a property and you want it included within a REIT, a stamp duty proposal is coming in to redefine it.
Lastly, the road maintenance levy, which is collected through the purchase of petroleum products, petrol and diesel. A bit of it goes into the roads annuity fund. Right now, we are paying 25 shillings (about 19 US cents) per liter as road maintenance levy, and three shillings (about 2 cents) of that goes into the roads annuity fund. The proposal is to reduce what goes to the roads annuity fund from three shillings to one shilling and 50 cents (about 1 US cent). Largely, this is what you call appropriations-in-aid, so it doesn’t have a bearing on the tax revenue we spoke about.
That’s a snapshot of the Finance Bill—quite lengthy, quite detailed. I hope I’ve done it justice in slightly over an hour. It’s my first time just giving a lecture like this, quite an interesting one. Anyway, you can now submit your written memorandum to the Clerk of the National Assembly; there’s an email there that you can see. You can also submit to the Finance Committee of the National Assembly; there’s an email there too. The deadline is next Monday, May 25, by 5 p.m. East Africa Time. There’s no extension, for sure—Kenyans, I know you with extensions. There’s no extension. By 5 p.m. you need to submit your memorandum on the bill. Thanks.
Keith Ang'ana
Thank you very much, Mr. Churchill. That was an amazing presentation, and it has been very enlightening, because the thing about the Finance Bill is that it’s a very tough document to go through, especially because you need to compare it with the previous acts—the Income Tax Act, the VAT Act—and it’s a very tedious thing. But you have been able to break it down for us, and we’ve been able to understand it. So first of all, thank you very much for that. You made it look easy.
Before we release you, there are a couple of questions that have come out of the discussion, and we’d like to put them to you so that you can shed some clarity, so that we understand as we go ahead to make our public participation submissions.
First of all, just a general question, an overview. Do you have an opinion on how this bill compares to last year’s Finance Bill? Is it fair to the citizens, or does it lean more toward the government in terms of collecting more revenue?
Churchill Ogutu
An apples-to-apples comparison will be slightly hard—I may not do it justice. If you look at what was targeted to be collected last year, I think it was KSh 35 billion (about $270 million) in the initial Finance Bill proposal. This time we have KSh 54 billion (about $420 million) that is targeted to be collected, and there’s another KSh 30 billion (about $230 million) from the tax amnesty. So the proposal this time around seems to be quite aggressive. And there are other aspects on the procedures—for instance, the filing, which we now need to front-load, rather than filing by June 30 the way we know it, bringing it two months earlier to April 30. Ostensibly, from what you hear, that gives the KRA some time to do reconciliations and all that, but obviously it will increase compliance costs, if you think about how people will try to implement this. Those are some of the things that stood out for me in the bill.
Keith Ang'ana
Okay. And just generally, as an economist, do you think that the more taxes are increased, the less the government possibly collects? Because from the Finance Bill 2024, there was this issue of the Laffer curve, whereby the government is trying to be more aggressive and increase regulations, but in the end, when the quarterly reports come out, the KRA usually misses its target. So do you think it’ll possibly be the same now, with the introduction of these many amendments on taxes?
Churchill Ogutu
If you look at it from where I started, the tax revenue target, if you compare where we are right now, the supplementary budget, with what is being targeted in the next financial year, there’s an increase of KSh 258 billion (about $2 billion), of which KSh 120 billion (about $930 million) is coming from this Finance Bill and the EAC tax amendments, which are also part of the Finance Bill. The balance, they say, will come either from tightening administrative measures, or they’re just banking on the economy continuing to boom, so that revenue will continue. Remember that you still have the existing tax laws as they are. The Finance Bill, the 57 clauses, is just seeing avenues for other revenue measures.
Out of these KSh 258 billion (about $2 billion), KSh 120 billion (about $930 million) is coming from these new measures. So they’re also hoping that what they collected this financial year, ending in June—however little it is—continues. But already, looking at the numbers up to April and comparing them to where they ideally should be, it points to the fact that they might miss the target. There’s another aspect, what you call tax buoyancy: You look at the percentage growth in tax revenue against the percentage growth in nominal GDP. If the growth in revenues is more than the growth in GDP, that means they can meet their revenue target. But the numbers for the next financial year show that number is below one—it’s 0.7—so the assumption is that the economy is growing faster than they can collect revenue.
A number of things feed into that. You’re largely looking at the formal sector. On the individual side, you’ve seen that disposable income has pretty much shrunk. On the corporate side, the analysis even in the Economic Survey shows that, as much as profits from businesses are quite significant, they’re not growing as fast as they used to. So the taxes expected from income taxes, whether individual or corporate—or even if you look at consumption, because disposable income has shrunk, you’re not consuming as much as you used to. This feeds into the negative revenue performance we’ve seen, and it challenges the point in your question: We are doing all these tax proposals, yet we know we may not even hit the target, so why do it? It’s still a debatable issue. But ultimately, you may find they are caught in a catch-22.
Step back: We had the medium-term revenue strategy, being implemented in two phases. The first phase started in July 2024 and is supposed to end by June 2027. They’re looking at it in terms of tax revenue to GDP. When they wanted to start it off, it was 14.3 percent tax revenue to GDP; the goal was to increase it to 20 percent. That’s what they were looking at in July 2024. There were some measures in that medium-term revenue strategy which potentially could have benefited people: They were looking at reducing VAT from 16 percent gradually, possibly to 14 percent; the corporate tax rate from 30 percent to 25 percent; the PAYE top band from 35 percent to 25 percent. But we missed the boat—June 2024 happened, and it went back. So even now, they still haven’t reached there. You can pity the government that they want to reach 20 percent, but even looking at the numbers for the next financial year, we are still at 14 percent.
We haven’t even moved, even within the context of implementing this medium-term revenue strategy. So you can pity them, but you also have to be alive to the economy—the economy probably is not solid enough to support higher taxes, or these tax proposals.
Keith Ang'ana
Yes, thank you. I think that sheds more light on it. On that note, I wanted to ask some questions about the specific amendments. This is something you’ve mentioned already, but some clarity was needed on the particular point of section 6A of the Excise Duty Act, imposing a 25 percent tax on mobile phones at the time of activation. The question that’s been asked is: At what particular point in time can we say a phone is activated? Is it when it’s been imported, or when it’s turned on? How will this work?
Churchill Ogutu
I think more of the latter, at the point where you turn it on, rather than at the point of importation. Ideally this stuff happens at the point of importation, whereby as you import these goods, you have the import declaration forms and all the requisite taxes and levies you have to pay. But this time, from the look of things—or the intent of this, if it sails through—you don’t pay them at that point, but at the point of activation. And that raises legitimate concerns: What is activation?
Keith Ang'ana
And is it levied on the importer and then transferred to the buyer, or directly on the buyer? It seems like—
Churchill Ogutu
It seems like it’s on the buyer, at the point of activation of the phone, because the buyer is the one who has to activate it. So it means that even the purchase price will have to go up by 25 percent, because that’s the excise duty being slapped on at the point of activation. So it’s on the buyer—the consumer, ultimately.
Keith Ang'ana
Okay. The next question, because this is something that has generated a lot of heat on Twitter: There’s section 24 of the Income Tax Act, which provides the KRA with powers to tax companies on their retained profits—something about if a company does not pay out at least 60 percent of its profits as dividends, the KRA will treat part of the remaining profit as deemed dividends and go ahead and tax it. So first of all, have you seen that part? And the question being asked is whether this would choke businesses and make them lose the incentive for which they carry out their operations, because now the KRA will also be taxing more of the profits that haven’t been paid out as dividends. So the question is: What has been the practice with the KRA and dividends, and what does that section actually mean?
Churchill Ogutu
This section brings a different interpretation of what a deemed dividend is. Initially, the wording was that they considered a portion of the income. The example I gave: You have revenues of, say, KSh 1 million (about $7,700); expenses of KSh 600,000 (about $4,600); so you have profit of, say, KSh 400,000 (about $3,100), assuming you don’t have anything other than that. Part of it you can say is retained earnings; part of it could be taken through. But the assumption here is that there’s tax avoidance, in a way, by not distributing dividends. They need to look at why you are not making dividend payments—there could be a myriad of reasons behind that—whereas the lens being used, as it is, is that whatever profit you have, you have to be paying a portion of it as dividends. The underlying assumption is that at least 60 percent of what you did not distribute is now deemed to be the dividend paid to your shareholders. But it assumes a number of things. It assumes you just have money there that ideally you should be distributing as dividends—but potentially you could be retaining it; you could be trying to expand the business, or timing investment decisions for the future. So it’s not that you have to distribute it as dividends, but the requirement, as it is in the proposal, is that you should be distributing it as dividends. Other than that, they just assume at least 60 percent of it should be treated as if it’s been distributed—which might not necessarily be the case. That’s what’s problematic about this particular proposal.
Keith Ang'ana
So when the proposal says at least 60 percent, does it mean the baseline is 60 percent and the KRA can go up, if they want, to a particular percentage?
Churchill Ogutu
Yeah, that’s the thing, because it speaks about at least 60 percent. So in the assessment they may say: We’ve looked at you, and probably it’s 100 percent that you disbursed as dividends, and you have to pay tax on that distributed dividend—as it is, because it’s a deemed dividend. Ultimately, the KRA is the one coming in and saying 100 percent is what you distributed to your shareholders, when probably you didn’t even distribute to shareholders. But that’s the assumption this particular proposal is hinging on.
Keith Ang'ana
Just based on that: There’s the problem of how the KRA has been given more interventionary powers to audit people’s accounts, including their banks and their M-Pesa, to demand tax, and to punish non-compliance with fines. Do you think it’s advisable to give the tax body these powers?
Churchill Ogutu
I think, by and large, the KRA already has the necessary tools to conduct whatever audit they might want on a taxpayer. I think this particular proposal is the one that speaks about how, over and above the self-assessment, they can independently conduct their own assessment. At least it has to be within the current framework; it shouldn’t infringe on your privacy. The moment it goes into that, it negates data protection—because time and again, finance bills bring up this issue around data protection, with the KRA coming in and infringing on the data protection laws we enjoy as Kenyans. Ultimately it has to be within a certain framework. I believe they can’t assess unless they come up with some tools—I don’t know what tools they’re looking at to do assessments. But I think they might be targeting some of these other professionals, in my view, who are not within this ambit, because time and again they’ve been saying that the formally employed are the ones under personal income tax. We have other professionals—doctors, lawyers, professionals who don’t fit, who don’t get the salaries subject to this kind of personal income tax regime. So unless they want to widen the tax bracket to home in on some of these—ultimately, it has to be within a proper framework, not infringing on privacy, and within the context of data protection laws.
Keith Ang'ana
Okay, great. The next question touches on section 12 of the Tax Procedures Act, which basically states that a foreigner shall be exempt from the requirement of having a KRA PIN when opening an account with an investment bank. The question being asked is: What might be the motive for this, and might it by any chance increase the chances of fraud?
Churchill Ogutu
Ah, well, that’s at the heart of my bread and butter, because I’m an investment banker. Typically, as part of KYC, any local who opens an account with an investment bank has KYC documents required of them: a national ID, a PIN, not necessarily a bank statement, those kinds of things. Some of those also apply to foreign investors who want to invest in the Nairobi Securities Exchange—they’re required to have their passports, and they’re also required to have a PIN for the purposes of taxation. But now this is being removed. As I mentioned earlier, it tends to be a lengthy process for a foreigner to acquire a PIN in the country, so they’re just removing this compliance burden, which is part of the KYC documentation. I think it’s quite good. The motive is probably to stimulate foreign investment—or rather, foreign equity portfolio flows. Investors who invest in the Nairobi Securities Exchange are called portfolio investors, not foreign direct investors. So they want to stimulate that activity. It could be beneficial, as I said, within the investment bank—it’s something that’s quite welcome to us.
Keith Ang'ana
Something that you deal in. Okay, so it seems like we’re not done with section 24, because people still have more questions on it. The issue is that dividend distribution tax is already captured under corporate tax, meaning the income is already taxed. So does the introduction of this mean the KRA is placing a tax on top of another tax?
Churchill Ogutu
Quite an interesting one. You look at it to the extent of the businesses. I was just assuming a simple business where you have your profits, and then you can declare dividends—the same way Safaricom, for instance, recently declared a dividend on part of its profit. That dividend is paid from the profits. But before you get to the profits, there are the other expenses that have already been paid, which may typically exclude the payment of dividends. So in this scenario, it’s now the deemed dividend—the one they just assume you were supposed to have paid but did not pay out to your shareholders. I think that’s pretty much where they’re coming from with this proposal: this income—why haven’t you paid it as dividends? But it raises another conversation around how they’re sort of chaperoning all businesses into paying dividends as a must. Like, you have to pay dividends as a must, or the counter is that if you don’t pay dividends, it’s at the discretion of the KRA—at least 60 percent of whatever remains is now deemed as a dividend that was paid. I think that’s the heart of it.
Keith Ang'ana
Yeah, and I think you’ve just touched on this with your last statement. But the question being asked, which I think is a very tough question, is how this new change affects alignment with the Companies Act regarding dividend policy autonomy.
Churchill Ogutu
Those are the issues that come to the fore as you start implementing some of these proposals, and I think, by and large, we’ll keep hearing them in the context of the ongoing public participation, because they bring other angles that the framers of the bill potentially had not considered in the first instance. That’s why we have to give our submissions by next week Monday, to bring out some of these issues. But that’s a legitimate issue, because now you’re interfering with the dividend policy of a company.
Keith Ang'ana
Okay. We already saw a drop in the money being transacted through M-Pesa in the latest Kenya National Bureau of Statistics report. Now this Finance Bill actually proposes taxing mobile money more. Please elaborate on that section of the bill and maybe touch on its effect on people and the economy—since of course there’s a lot of digital money penetration, and we as a country are known for M-Pesa.
Churchill Ogutu
That speaks to the aspect of interchange fees—the inclusion of interchange fees, cards, and a whole array of payment platforms within the ambit of withholding tax. I think we first need to get better clarity on what the intention was, because on one hand, if you hear from the National Treasury, it’s like they’re targeting the providers of payment cards; that’s what they were keenly pursuing. Yet at the same time, mobile money payment is also part of payments—you can also make payments through virtual cards, or through mobile. So clarity needs to be sought on who is being pursued by this particular proposal. But obviously, if you look at it in the context of mobile money, assuming that will be within this ambit and subject to this withholding tax, it will definitely increase transaction costs—which I don’t think is the intention, looking at the Economic Survey data showing that transactions have somehow slowed down in the economy. As you increase transaction costs, obviously it will dampen the mobile money transactions we’re seeing in the economy.
Keith Ang'ana
The other question being asked is that Mbadi, and also President Ruto, had promised to look at the tax bands and lower PAYE—and, of course, you mentioned this within the medium-term revenue strategy—where the current top PAYE rate of 35 percent is higher than the 30 percent corporate rate, contrary to the national tax policy, which recommends that individuals should not be taxed more than companies. Is it feasible to just reduce PAYE?
Churchill Ogutu
Is it feasible to reduce PAYE? That was contained in the medium-term revenue strategy and the national tax policy: harmonizing the corporate tax, which was to be lowered from 30 percent to 25 percent, and also ensuring that the individual tax rate—the top band of PAYE—comes down from 35 percent to 25 percent. Because as it is right now, you’d rather pay the corporate tax rate, because it’s lower than the top band at 35 percent, depending on the income band you’re in. Remember this is graduated: Currently the first KSh 24,000 (about $185) is at 10 percent; the next KSh 8,333 (about $64) is at 25 percent; and then from KSh 32,333 (about $250) all the way to KSh 500,000 (about $3,900) at 30 percent, and so on. So I think they might have to do some simulations, not just look at reducing PAYE and whether it’s feasible. Because if you reduce it, it will lead to money being returned to people’s pockets, and then they’ll be able to consume more. So you’re reducing this, but you can see VAT going higher as a result. The last time, the National Treasury mentioned there are simulations ongoing.
Tied to that, speaking of zero-rating: That proposal came in around February, when we had CS Mbadi saying that the first KSh 30,000 (about $230) will be zero-rated. Remember, we don’t have a zero rate—the first KSh 24,000 (about $185) is at 10 percent; there’s no 0 percent, but we have a personal tax relief; everyone gets KSh 2,400 (about $19) in relief. So the way to think about this zero-rating: Is it that people who earn below KSh 30,000 (about $230) on a monthly basis get 0 percent? Also remember it’s a graduated scale, so if you’re earning KSh 200,000 (about $1,500), your first KSh 30,000 in this framework would be 0 percent—will it be applicable to everyone, because of the graduated scale as we know it, or will it be limited to people at or below KSh 30,000 shillings, so that they get 0 percent? And then the next band, between KSh 30,000 and KSh 50,000 (about $390), will reduce from 30 percent to 25 percent. So technically you’re jumping from 0 percent to 25 percent. And does it mean that, assuming the corporate tax rate comes down to 25 percent, everyone else. . . . ? There are a few things still up in the air; we need clarity around that.
In addition, we’ve been hearing—and I also mentioned this earlier—that they want to introduce PAYE even to some professionals who currently are not salaried employees, in consultancy or otherwise; they want to bring them within the PAYE regime. Is it that, as they do this for low-income employees—because I think the target is everyone below 50,000 (about $390), who one way or another are getting some form of relief—they now want to offset it with these professionals coming on board? Those are some of the things being worked out right now, from my sense.
But now the question is: We’ve seen the Finance Bill, and people are now doing public participation on the Finance Bill as it is. If they want to introduce this and have it passed by June 30, it means they will introduce an amendment well after the public participation stage has come and passed. We’ve been telling people they need to give their submissions by next week Monday. That closes. And then much later—because typically there’s the first reading of the bill, which is literally a first reading: This is the Finance Bill 2026, it proposes to make amendments, blah blah blah. Then it goes to the second reading stage, where there’s a report by the Departmental Committee on Finance and National Planning. This report also incorporates the public participation, and then Parliament debates the report—the merits of the current 57 proposals.
But then at the same time, it introduces some amendments before it goes to the third stage. So if this particular proposal is introduced, we’re looking at it being introduced well after the public participation has been conducted. Potentially, as I said, will they go for zero-rating, or will they—I don’t know—increase? I don’t know what modalities they’ll use. Some of them may be prohibitive, but people won’t get a chance to weigh in on them, because it will be well after the public participation. Those are the things that are still mind-boggling—how they’ll go about it. Or does it mean that, if this Finance Bill window closes, they introduce a tax amendment bill further down the line? That would be around six months from now, December thereabouts. So it’s still up in the air at this point.
Keith Ang'ana
Okay, and I think that’s a great point on which to finish up. It’s been an amazing session. Thank you very much once again. Just as we end, I want to ask you to remind us how to make our views known to Parliament. If you can take us through the submission process one last time.
Churchill Ogutu
You can submit your written memorandum—you can actually write it. I know I’m speaking to. . . . there’s normally this debate about the millennials and the Gen Zs. So for the millennials, and those who are Gen X and all that, you can hand-deliver it to the Office of the Clerk, first floor, Main Parliament Buildings, Nairobi. You know where it is. I don’t know whether this will be applicable to other people, because this is not just a Nairobi affair; it’s also for people in other parts of the country. If you’re not able to hand-deliver your written or printed submission to the Office of the Clerk, you can send an email to the Clerk of the National Assembly, which you can see on the screen, [email protected], and also to the Finance Committee, chaired by the Honorable Kuria Kimani, at [email protected]. The deadline is 5 p.m. next Monday, May 25—East Africa Time. There’s no extension. By the way, that will be the day after a team in North London lifts the league. Remember: You lift the league first on Sunday, and then on Monday you submit. Whichever sequencing you want—lift the league first and then submit, or submit and then lift the league—you have to submit by next week Monday, 5 p.m. East Africa Time [Submissions have since closed. The email addresses above are given as they were shared during the lecture.].
Keith Ang'ana
Yeah, and they should look out for any public hearings that will be happening.
Churchill Ogutu
Yeah.
Keith Ang'ana
Yes, thank you very much, and I think we have come to the end of this. Shukran sana.
Churchill Ogutu
Thank you for having me.